Roof Certification Letters for Home Sales & Insurance Pensacola
When an insurer, lender, or buyer asks for roof documentation, the first step is understanding exactly what they need—because a 'roof certification letter' can mean very different things depending on who is asking. We provide roof condition documentation and evaluations across Pensacola and Escambia County for real-estate transactions and insurance reviews, and we help homeowners confirm the specific document, format, and information the requesting party requires before scheduling.
A 'roof certification letter' can mean different things depending on the insurer, lender, or real-estate transaction. Before scheduling, homeowners should identify exactly what documentation, inspection format, roof age information, or remaining-useful-life statement has been requested. Documentation requirements vary, and a roof condition evaluation may review the covering, flashing, penetrations, leaks, and deck evidence—but homeowners should confirm what the requesting party specifically requires.
When Roof Documentation May Be Requested
Roof documentation is requested at the points where a property's roof condition matters to a transaction or a coverage decision. A buyer wants to know the roof is sound. An insurer wants to know the roof's age and condition before binding or renewing coverage. A lender wants assurance the collateral is protected. Each situation asks a slightly different question, and the document that answers it should match the question being asked.
- Home sale—buyer due diligence on the roof's condition and remaining life
- Home purchase—lender or insurer requirement before closing
- Property insurance application—roof age and condition for underwriting
- Insurance renewal—carrier request for updated roof documentation
- Underwriting review—roof condition affecting coverage terms
- Older roof—insurer request for condition verification on an aging roof
- Known roof repairs—documentation that prior repairs were completed
- Real-estate due diligence—pre-listing or pre-purchase roof assessment
A roof certification or condition evaluation is separate from a standard whole-home inspection. A home inspection is a broad survey of the entire property; a roof-focused evaluation examines the roof system specifically. When a transaction requires roof documentation, a dedicated roof evaluation provides the focused detail the requesting party needs.
What a Roof Condition Evaluation May Review
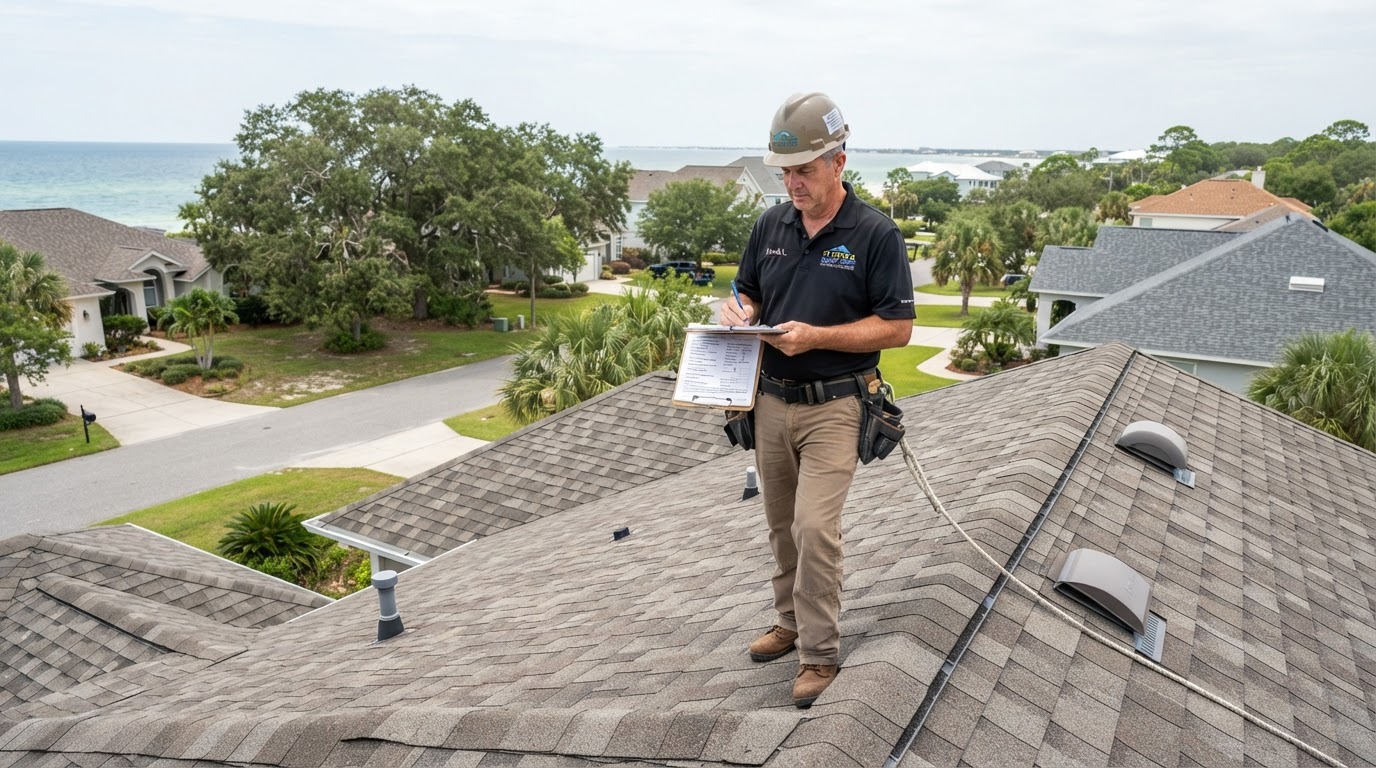
A roof condition evaluation examines the roof system as it exists on the day of inspection. It documents what is visible and accessible and reports on the condition of the components that determine whether the roof is watertight and serviceable. The evaluation is observational—it reports what is found, it does not certify a specific remaining lifespan as a guarantee.
- Roof covering—the shingle or metal surface and its visible condition
- Visible deterioration—curling, cracking, granule loss, or corrosion
- Missing or damaged materials—shingles, panels, or components that need attention
- Flashing—condition of step, valley, and penetration flashing
- Penetrations—pipe boots, vents, and skylights and their sealing
- Leaks—evidence of active or past water intrusion
- Roof deck evidence where accessible—softness or water staining from the attic
- Repair history when documented—records of prior roofing work
- Approximate age when records exist—installation date from documentation
We do not fabricate a roof age without documentation. If installation records, permits, or prior inspection reports exist, they support an approximate age. If no documentation exists, the age is estimated from visible condition and cannot be stated as a verified fact. Honest documentation serves the homeowner and the requesting party better than a guess presented as certainty.
Roof Certification vs 4-Point vs Wind Mitigation
These three inspections are often confused, but they answer different questions and produce different documentation. Submitting the wrong inspection to an insurer or lender can delay a transaction or a coverage decision. The exact inspection must match what the requesting party requires, which is why confirming the requirement first matters.
| Inspection | What It Covers | Common Use |
|---|---|---|
| Roof Condition / Certification | Roof-focused evaluation of the covering, flashing, and condition | Home sales, insurer roof-age or condition requests |
| 4-Point Inspection | Roof, electrical, plumbing, and HVAC systems | Older-home insurance applications and renewals |
| Wind Mitigation Inspection | Documents qualifying wind-resistant features | Insurance premium discount verification |
The exact inspection must match what the insurer or requesting party requires. A roof condition evaluation does not substitute for a 4-point inspection, and a wind mitigation inspection documents different features entirely. We help homeowners identify which documentation they need before scheduling so the evaluation produces what the requesting party will actually accept.
Related inspection resources
Repairs Before a Home Sale or Insurance Review
A roof condition evaluation sometimes identifies issues that the requesting party wants addressed before documentation is issued or a transaction proceeds. These are typically the same minor-to-moderate failures that turn up in any roof inspection—missing shingles, damaged pipe boots, flashing defects, or active leaks. Addressing them before the sale or insurance review can smooth the process, though it does not guarantee a specific underwriting outcome.
- Missing shingles—exposed areas that a buyer or insurer may want repaired
- Damaged pipe boots—cracked seals that are an obvious leak risk on documentation
- Flashing defects—lifted or failed flashing that compromises watertightness
- Active leaks—water intrusion that must be resolved before any certification
- Damaged ridge caps—wind-damaged caps that signal storm exposure
- Deteriorated metal panels—corrosion on metal roofing that affects condition
- Roof age concerns—an aging roof that may require replacement rather than certification
We do not promise insurance eligibility after repairs. Completing repairs can improve a roof's documented condition, but coverage decisions are made by the insurer based on their own underwriting criteria. We document what we find and what was corrected; the insurer determines whether that meets their requirements.
Common pre-sale repair services
Confirm What Your Requesting Party Needs
The most common reason roof documentation does not satisfy an insurer or lender is that the wrong evaluation was performed. A roof certification is not accepted where a 4-point inspection is required, and a wind mitigation inspection documents features the other two do not. Before scheduling any roof evaluation, confirm exactly what the requesting party has asked for.
- What specific document has been requested—certification, 4-point, or wind mitigation
- What inspection format the requesting party requires
- Whether roof age or remaining-useful-life information is needed
- Whether repair documentation or prior inspection records are required
- Whether the insurer has a specific form or format they accept
- Whether a deadline is tied to a closing or renewal date
We do not state that this business is automatically authorized to issue every form of insurance certification or inspection document, and we do not guarantee that a letter will be accepted by any particular insurer, lender, buyer, seller, or underwriter. Documentation requirements vary, and homeowners should confirm what specific document the requesting party requires before scheduling.
Frequently Asked Questions
Need Roof Documentation for a Sale or Insurance Review in Pensacola?
Contact Pensacola Metal & Shingle Roofing Contractors for a detailed written estimate across Pensacola, Escambia County, and Santa Rosa County.
Request Your Roofing Estimate
Direct consultation for Pensacola & Escambia County residential and coastal properties.